
The Foreign Investment in Real Property Tax Act (FIRPTA), enacted in 1980, requires foreign persons to pay U.S. income tax on the gains they make from selling U.S. real estate. FIRPTA applies to the sale of interests held by nonresident aliens and foreign corporations in real property within the United States. FIRPTA imposes a duty on the buyer in the transaction (but if not handled properly sometimes the title company) to deduct and withhold a portion of the sales price to send and report to the Internal Revenue Service.
While there are several exceptions to withholding, only two are commonly relied upon for a traditional resale transaction. In general, when you have a transaction that falls under FIRPTA the presumption is that the withholding needs to be done through closing. The responsibility then falls to the seller to “qualify” for the exception.
If the following conditions are met a “personal residence exception” exists and the withholding amount can be reduced or waived:
If the transaction qualifies based on the above criteria, the seller may have the withholding amount reduced or waived according to the chart below.
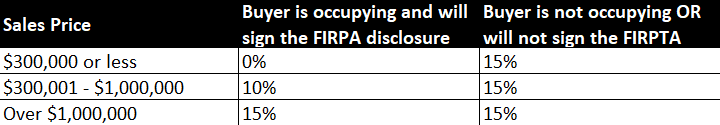
*Note that the percentage to be withheld is from the sales price, not seller proceeds.
*Also, note that the Texas Real Estate Commission contracts require that the seller sign an affidavit to state that they are not a foreign seller. All sellers are required to sign this form at closing - it should be included in the closing package.
Another way for the seller to avoid FIRPTA withholding is to obtain a withholding certificate issued from the IRS. This requires the seller to submit to the IRS for the certificate prior to closing. It is important to note that this process can be lengthy so any seller seeking to use this option should begin working on it well before they go under contract.
Law Offices of Latra Szal, PC Contact Us: 512-317-3646 Latra@REDocPrep.com
Contact
Latra Szal - Lawyer Site
© 2026 Latra Szal - Lawyer Site. Powered by RealSavvy